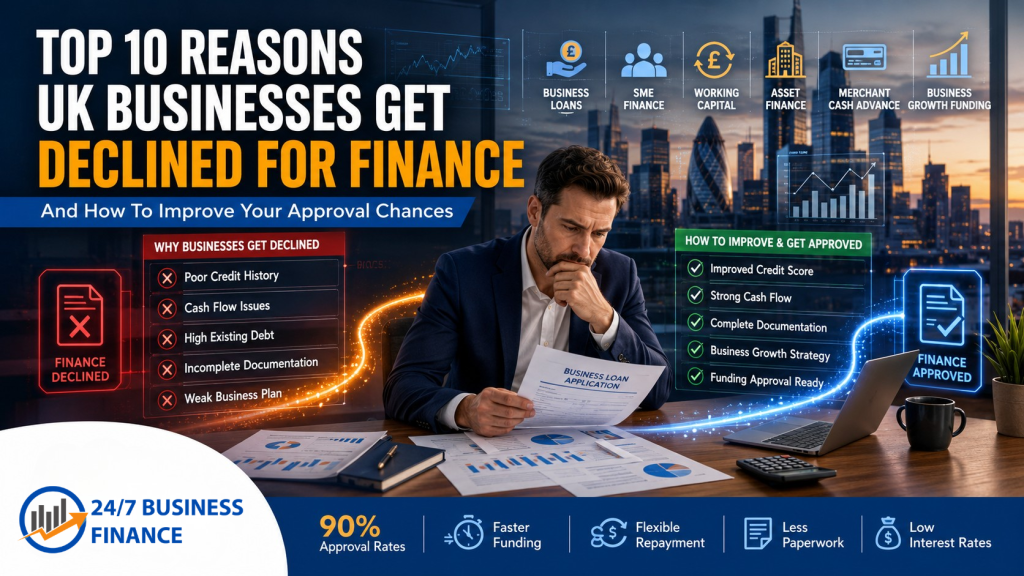
Top 10 Reasons UK Businesses Get Declined for Finance (And How to Avoid Them)
Securing business finance is often essential for growth, expansion, cash flow management, equipment purchases, and working capital. However, many UK businesses are surprised to discover that their finance application has been declined.
Whether you’re applying for a business loan, asset finance, merchant cash advance, or working capital funding, understanding why lenders reject applications can significantly improve your chances of approval.
In this guide, we’ll explore the top 10 reasons UK businesses get declined for finance and provide practical tips to help you secure funding successfully.
Why Do Lenders Decline Business Finance Applications?
Lenders assess risk before approving any funding application. They want confidence that the business can repay the borrowed amount while maintaining financial stability.
A declined application doesn’t necessarily mean your business is failing. In many cases, small issues within the application process can lead to rejection.
If you’re currently looking for funding solutions, explore our comprehensive range of business finance options at:
1. Poor Credit History
Why It Matters
One of the most common reasons for finance rejection is a poor credit profile.
Most lenders review:
- Business credit score
- Director credit history
- Previous loan repayments
- County Court Judgments (CCJs)
- Defaults and missed payments
A poor credit record signals increased risk to lenders.
How to Improve Approval Chances
- Check your credit reports regularly.
- Pay suppliers and creditors on time.
- Resolve outstanding CCJs where possible.
- Avoid multiple credit applications within a short period.
According to Experian UK, maintaining a strong credit profile can significantly improve borrowing opportunities.
External Resource:
https://www.experian.co.uk/business-express/business-credit-score
2. Insufficient Cash Flow
Why Lenders Are Concerned
Cash flow demonstrates your ability to meet financial obligations.
Even profitable businesses can struggle if cash flow is inconsistent.
Lenders often review:
- Bank statements
- Cash flow forecasts
- Management accounts
- VAT returns
How to Strengthen Your Position
- Maintain positive cash reserves.
- Improve debtor collection processes.
- Reduce unnecessary expenses.
- Consider a Working Capital Loan to support short-term cash flow requirements.
Learn more about:
https://www.247businessfinance.com/our-services/
3. Lack of Trading History
Startups Face Additional Challenges
Many traditional lenders prefer businesses that have been trading for at least 12–24 months.
New businesses often lack:
- Financial statements
- Proven revenue
- Historical performance data
Solutions for Startups
If you’re a newer business, consider:
- Startup Loans
- Government-backed schemes
- Alternative lenders
- Asset-backed funding
Our specialists help businesses access suitable startup funding solutions tailored to their circumstances.
4. Incomplete Documentation
Missing Information Causes Delays and Rejections
A surprising number of applications are declined because required documents are missing.
Commonly requested documents include:
- Business bank statements
- Identification documents
- Company accounts
- Tax returns
- Business plans
Best Practice
Prepare documentation before applying to avoid unnecessary delays.
Visit our Customer Service section for additional support:
5. High Existing Debt Levels
Debt-to-Income Ratios Matter
Lenders assess current borrowing commitments carefully.
Excessive existing debt may indicate that your business is already financially stretched.
Examples include:
- Outstanding business loans
- Credit card balances
- Overdraft usage
- Asset finance agreements
What You Can Do
- Consolidate expensive debt where appropriate.
- Reduce outstanding liabilities.
- Demonstrate a clear repayment strategy.
6. Weak Business Plan
Particularly Important for Startups
A poorly structured business plan can significantly reduce lender confidence.
Lenders want evidence that:
- Your business model is viable.
- Revenue forecasts are realistic.
- Growth plans are achievable.
Essential Elements of a Strong Business Plan
Executive Summary
Clearly explain your business goals.
Market Analysis
Demonstrate understanding of your target market.
Financial Forecasts
Provide realistic projections supported by data.
The UK Government offers guidance on creating effective business plans:
7. Industry-Specific Risk Factors
Some Sectors Are Considered Higher Risk
Certain industries experience greater volatility and therefore attract stricter lending criteria.
Examples include:
- Hospitality
- Construction
- Retail
- Seasonal businesses
This doesn’t mean funding is unavailable. It simply means lenders may require additional evidence of stability.
Specialist Finance Solutions
Working with an experienced finance broker can help identify lenders familiar with your industry sector.
Learn more about our expertise:
8. Inconsistent Revenue Performance
Revenue Stability Matters
Lenders look for predictable income streams.
Warning signs include:
- Significant monthly fluctuations
- Declining sales trends
- Seasonal dependency without mitigation plans
Improve Your Application
Provide:
- Up-to-date management accounts
- Revenue forecasts
- Customer contracts
- Purchase orders
These documents can strengthen lender confidence.
9. Applying for the Wrong Finance Product
One Size Does Not Fit All
Many businesses apply for funding products that do not align with their objectives.
Examples:
| Business Need | Suitable Funding Option |
|---|---|
| Equipment Purchase | Asset Finance |
| Short-Term Cash Flow | Working Capital Loan |
| Card Sales-Based Funding | Merchant Cash Advance |
| Property Purchase | Secured Business Finance |
| Growth Capital | Unsecured Business Finance |
Choosing the right funding solution can dramatically increase approval rates.
Explore available options:
10. Lack of Security or Collateral
Why Security Matters
Some lenders require security to reduce risk.
Common collateral includes:
- Commercial property
- Equipment
- Vehicles
- Other business assets
Alternative Solutions
Businesses without significant assets may still qualify for:
- Unsecured Business Finance
- Merchant Cash Advances
- Revenue-based funding
- Startup loans
An experienced finance broker can identify suitable lenders based on your circumstances.
How a Business Finance Broker Can Improve Approval Chances
Working directly with a single lender can limit your options.
A specialist broker can:
- Compare multiple lenders
- Match applications to lender criteria
- Reduce unnecessary credit searches
- Improve approval prospects
- Secure competitive rates
At 247 Business Finance, we work with businesses across the UK to identify suitable funding solutions for growth, expansion, and cash flow management.
Discover the benefits of working with us:
Key Takeaways
Finance applications are often declined for reasons that can be addressed before submission.
The most common reasons include:
- Poor credit history
- Insufficient cash flow
- Lack of trading history
- Missing documentation
- High debt levels
- Weak business planning
- Industry-related risks
- Inconsistent revenue
- Applying for unsuitable finance products
- Lack of security
By understanding lender requirements and preparing properly, UK businesses can significantly improve their chances of securing funding.
Need Help Securing Business Finance?
Whether you’re looking for a Startup Loan, Working Capital Finance, Merchant Cash Advance, Asset Finance, or a Secured Business Loan, our specialists can help you compare options from a wide range of UK lenders.
Get a free quote today:
Or contact our team: